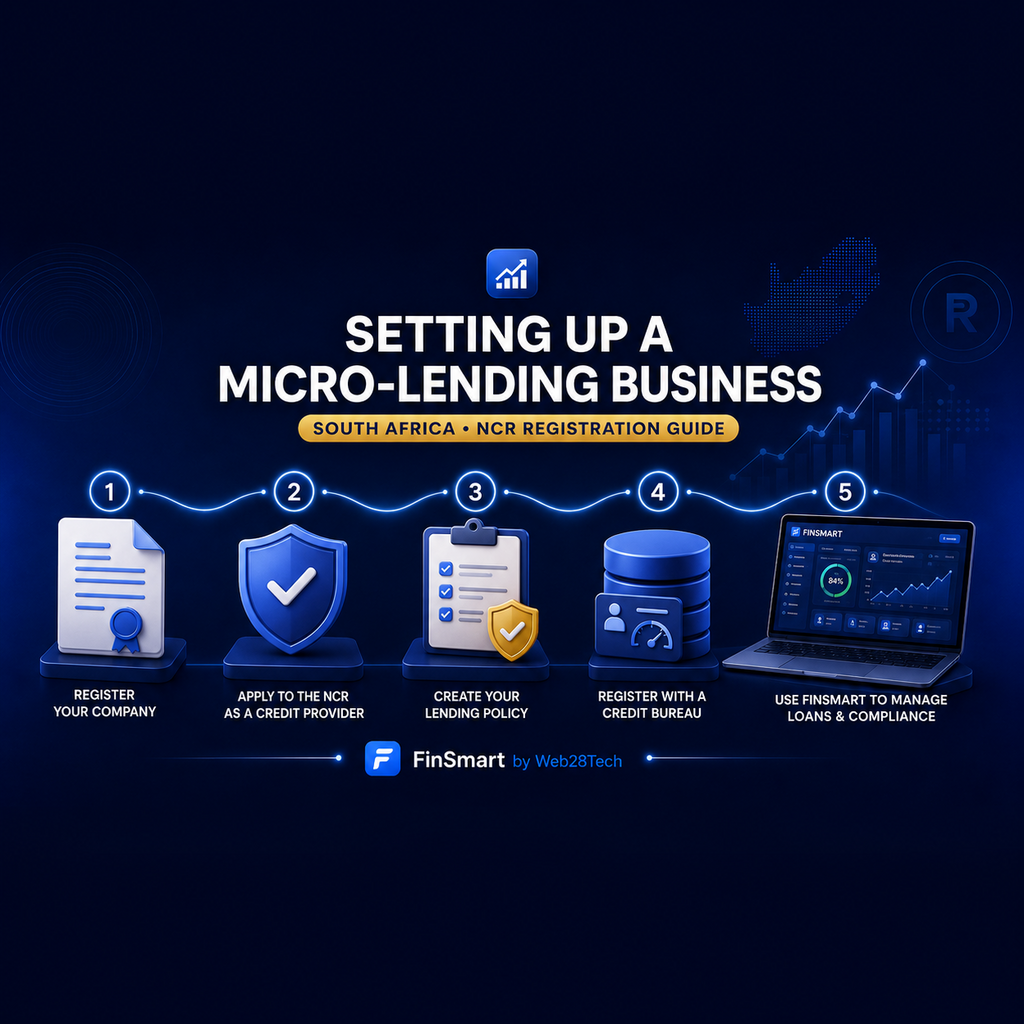
Setting Up a Micro-Lending Business in South Africa: NCR Registration Guide
A step-by-step overview of what's involved in starting a legally compliant micro-lending business in South Africa, from NCR registration through to your first loan.
South Africa's micro-lending sector serves a real need — access to short-term credit for people underserved by traditional banks. But starting a lending business isn't as simple as having capital and a spreadsheet. It's a regulated industry, and getting the foundation right protects both your clients and your business. Here's the general path.
This is a general overview, not legal advice. Confirm specifics with the NCR or a registration consultant before acting.
1. Decide on Your Business Structure
Before approaching the NCR, register your business entity — most micro-lenders operate as a private company (Pty Ltd) via CIPC. You'll need this registration in place before applying for NCR credit provider status.
2. Understand When NCR Registration Is Required
Registration as a credit provider with the National Credit Regulator is mandatory if:
- You extend more than a small number of credit agreements, or
- The total principal debt under your agreements exceeds the threshold set by the National Credit Act
In practice, almost any micro-lending operation beyond informal, occasional lending to a handful of people will need to register.
3. Prepare Your NCR Application
The NCR application generally requires:
- Proof of company registration (CIPC documents)
- Tax clearance certificate
- Details of directors/shareholders, including fit-and-proper declarations
- A business plan outlining your lending model, target market, and credit policies
- Proof of the capital available to fund your loan book
- Your draft credit agreement template and pre-agreement disclosure documents
4. Build Compliant Lending Policies Before You Lend
Registration isn't the finish line — it's the starting point for ongoing compliance. Before disbursing your first loan, have documented policies for:
- Affordability assessment — a consistent method applied to every applicant
- Interest rate and fee structure — within NCR-prescribed maximums for your credit agreement category
- Pre-agreement disclosure — clear, plain-language terms given to clients before signing
- Collections and default handling — a process that follows required notice procedures, without harassment or inconsistent treatment
For a full breakdown of ongoing compliance obligations, see our NCR Compliance Checklist for Micro-Lenders.
5. Set Up Your Operational Systems Early
It's tempting to start on a spreadsheet "just to get going." The problem is that early habits are hard to unwind once you're managing dozens of active loans. Decide upfront how you'll:
- Track applications, approvals, and disbursements
- Record signed agreements and supporting documents
- Manage repayment schedules and send reminders
- Generate the reports the NCR may request during an audit
Lenders who start with structured systems from day one avoid the costly process of migrating a tangled spreadsheet history later.
6. Register with a Credit Bureau
NCR-registered credit providers are generally required to report to a registered credit bureau. This affects both your risk assessment on new applicants and your compliance obligations for existing loans.
7. Open for Business — With Compliance as a Habit, Not an Afterthought
Once registered, the real work is consistency: the same affordability check, the same disclosure process, the same documentation, for every client, every time. This is where many lenders quietly drift out of compliance — not through bad intent, but through manual processes that erode under day-to-day pressure.
Starting Right Saves You Later
The lenders who struggle most with compliance audits aren't the ones who cut corners deliberately — they're the ones who started without a system and never found time to build one. Setting up loan management software before your book grows past the point where spreadsheets work is far easier than migrating under pressure.
FinSmart is NCR-ready loan management software built for South African micro-lenders, from day one of operation through to scale. Book a free demo to see how it fits your setup.